Tuesday, February 28, 2006

Cassandra

Bill Gross, Chief Investment Officer of PIMCO, writes a monthly essay, the Investment Outlook. PIMCO is a large fixed income investor and Bill's essays are wonderful reviews of economic, fiscal, and public policy.

His current essay - The Gang Who Could Not Talk Straight - is a highly critical review of the President's annual Economic Report.

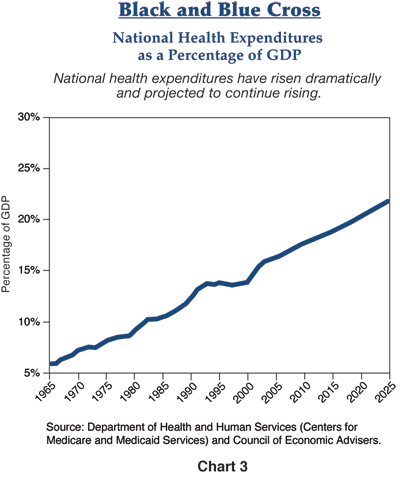
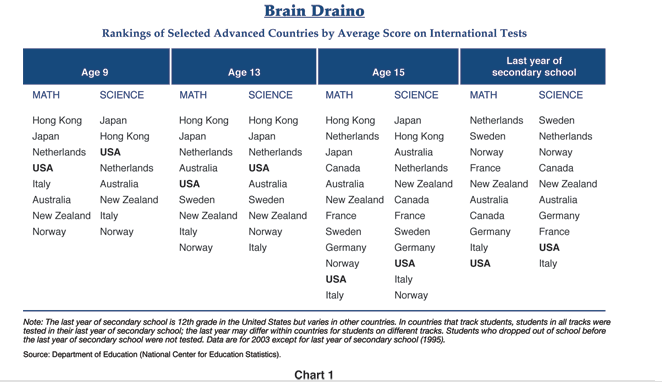
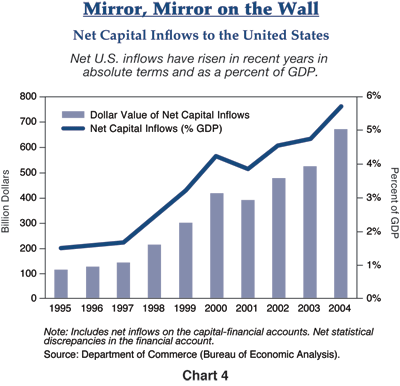
In short, he argues that America's competitive position is being undermined by a collapse in our educational systems, sky rocketing health care costs, the lowest national savings rates in the developed world, and an addiction to foreign investment to cover for our inability to save. His conclusion is that these macro failings demand that investors begin to ship capital offshore to more attractive markets. His warnings, however, are important for all to hear. Hopefully, he and others like him, see Pete Peterson, will not be seen as Cassandras, but as concerned patriots helping us wake up to our daunting realities.

As investors, entrepreneurs, and technologists, we have a vital interest in functioning educational systems, health care markets, and positive net savings rates that allow for investment in the future rather than debt service payments to cover historical obligations and spending. If Gross Domestic Investment = Private Saving + Government Saving + Foreign Saving, then the low rate of private and government savings demands that we import capital. The key concerns are 1) that the debt service associated with the current borrowings drowns out the ability for net new investment or 2) foreigners stop providing us cheap capital and dollars available for investment (and hence growth) are limited.

A couple of his charts help tell the story.

Sunday, February 19, 2006

Broadcast versus Subscription Business Models

At Hummer Winblad, we are seeing a tremendous number of innovative consumer-facing subscription services. Be it on-line storage, photo sharing, social networking, or other creative ideas, there appear to be a myriad of businesses emerging that are dependent on subscription-based business models. A major challenge looms for these young companies in that the major Internet companies' business models - Yahoo, Google, AOL, and MSN, are based on broadcast economics. Their revenues are are tied to page views and ad impressions rather than recurring application revenues. Accordingly, many of the consumer companies we meet with boast great teams and compelling technology, however, their business models are orthogonal to the business models of the dominant Internet companies, whose models allow them to aggregate and provide compelling services and content for free.

Broadcast companies are incented to provide the best content and services possible to draw in more users, more page views, and more ad impressions. Broadcast businesses seek to maximize revenue per impression/costs per impression, and the wonderful scale these models have achieved with respect to ads sales, affiliate models, and infrastructure costs provide for rich marginal profit margins. Scale allows for economics of scope, whereby they can offer great services - for free - knowing that their costs to offer the service are far lower than competing pure-plays and that their ad businesses will reward incremental users and page views.

Subscription companies require a certain level of free to paid conversions to make sense. The challenge is that to compete with the free versions, vendors get caught in a feature battle, where each incremental feature is valued by an increasingly smaller pool of people. Google and Yahoo are able to hollow out subscription businesses, if and when they choose to enter a given market, and stand-alone companies without ad network revenues and dependent on subscription services suffer the consequences.

Subscription models are, in general, driven by four key areas: cost per acquisition, monthly average revenue per user (ARPU), free cash flow (EBITDA), and churn (cancellations/average users per period). Subscription models require a clear focus on acquisition costs, strategies to drive ever higher ARPU, and customer retention strategies. I meet with many companies who are well-versed in subscription economics, however, their business plans often do not sufficiently factor in the power of broadcast/ad models to challenge their revenue models.

Internet broadcast models appear to be dominant on today's Internet. Unlike a focus on ARPU and churn, broadcast models seek to optimize their ability to profile their user base and to serve increasingly relevant adverstisements to their users. Competition centers not on conversion ratios, churn, and subscription revenues, but rather on powerful analytics, user segmentation, and behavioral analysis that allows for "perfect" ad targeting.

Each model relies on a different set of competencies and different set of goals. Consumer subscription models seek to entice free trial users to move to paid services, while broadcast models seek to maximize users and monetize them via advertising.

IMHO, when designing a model today, start-ups should focus on the type of model most likely to succeed - broadcast or subscription - knowing full well that the major players will continue to add functionality and services in a quest for more page views and ad opportunities.

PS. What is interesting to me is that on cable and radio, we are seeing the rise of subscription services challenging broadcast media - eg. HBO and XM Radio. This may be a function of FCC restrictions on broadcast content but is an interesting contrast to the current consumer Internet.

Monday, February 13, 2006

Stanford Panel on Software Trends and New Company Formation


This Thursday at Stanford, Hummer Winblad and BASES are hosting a panel on software trends and new company formation.

Please see the above flier for details. We are lucky to have a wonderful group of panelists committed to the event. Please feel free to attend if you are in the area.

Thursday, February 09, 2006

The Kiss of Death

Venture capital is often described as a business of pattern recognition - experienced investors pick up on market patterns, management team dynamics, and seemingly random data points to draw powerful insights. While I am still relatively new to the industry, I am struck by a few capital structure patterns that are generally bad omens.

The Too Large "A" Round
Ideal company formation reminds me of agile programming - small teams driving quick, iterative cycles that allow for the most insights, appropriate changes in strategy, and, ultimately, the highest quality "product."

I often say that genius is a function of context, and until a company is fully immersed in the context of the given problem set the best insights and strategies are often not apparent.

Too much money too early and too many people too early interferes with the productive process of iteration. Large teams with lots of resources and a very uncertain sense of direction or purpose are a bad combination.

Too High "A" Round Post-Money Valuations
While a self-serving argument, an equally challenging problem is a too high "A" round post-money. High "A" round valuations are often Pyrrhic victories. High posts and middling execution often leaves a company in a grey zone whereby objective value creating milestones have not been clearly met, yet some qualitative progress has been made. A common result of such a financing is a bridge round that extends the runway and is designed to allow the company a quarter or two to "grow" into its post-money "A" round valuation. More often than not, the bridge becomes a pier and the company and founders suffer from a post-money that proved you can win the battle and lose the war because of it.

"A" round financing strategies should be tied to discrete logic tests and proofs and the goal should be to optimize the validation/dollars ratio. Can we validate the technology and business model on as little as capital as possible? The ratio forces founders to think through the material questions that need to be answered with the use of proceeds. Will the product work? Will customers buy it? Can we sell it? If so, how? How much do we need, with a slight cushion, to answer these questions? Given all the noise in a start-up, what are the real issues and risks we need to manage? The validation/dollars ratio is a measure of efficiency and a quasi measure of return on equity. Start-ups that maximize the ratio are generally rewarded for it.

A reasonable Series "A" raise and post-money combined with realized value-creating milestones generally leaves a company in an enviable position when raising the Series " B". The key hypotheses have been validated and a reasonable mark-up is possible.

To that end, Cooley Goodward's recent report on trends in venture capital reported that the median Q305 valuations for A-D rounds were $5m, $12m, $23.5m, and $41.71m respectively.

Patterns and data suggest that for software companies an $8-10m "A" post appears to maximize the probability of a healthy B round and good optics and pattern recognition.

Wednesday, February 01, 2006

DEMO

I will be at Demo next week in Phoenix. Given all the dynamic activity in the start-up world, I expect to see some great new companies emerge from stealth in AZ.

To set up a time to meet or grab a drink, please ping me (wprice@humwin.com).

Sunday, January 29, 2006

Superbowl Index

As the pundits debate next Sunday's Superbowl, my friend Dave Cotter's company, Mpire, developed a Superbowl Index based on eBay's listings of Seahawk and Steeler paraphernalia. On average, Seahawk items sell for ~$50 more.

The Index is a clever means of showcasing Mprie's Researcher product and is probably as accurate as any TV pundit when it comes to forecasting a winner. It looks like whoever wins, eBay will take a cut along the way:)

Friday, January 20, 2006

1 (800) 411-METRO

Matt Marshall recently wrote an article on the $8bn directory services market and other emerging mobile information models. Matt profiles a recent addition to the HWVP portfolio, Infreeda.

Infreeda provides nation-wide, human operator, ad supported 411 calls. Very simply, dial 1 800 411 METRO the next time you are looking for a listing and stop paying high fees (~$1.75 per call) for information.

Let us know your feedback.

Thursday, January 19, 2006

Instant Gratification

Last night, Hummer Winblad hosted a dinner at Stanford for GSB, CS, and EE students. Stanford students are remarkably entrepreneurial and the energy around new company formation is impressive.

Over dinner, several questions were raised with respect to design considerations for new enterprise software companies. In thinking through an answer, the following thoughts came to mind.

What is the time to value quotient? How long does it take for the customer to realize value from your product? Compare and contrast clicking on a URL to self-provision versus a two-month on-premise proof of concept.

What is the customization to value quotient? How much customization is required before the customer sees relevance and value?

How much manual labor is required to realize value? How many sales engineering and professional services hours are required to both explain the merits of the solution and have it running successfully in the customer's environment? The common element of MySQL or Salesforce.com appears to be that customers self-validate through low-risk experimentation without the need for vendor sales engineers.

What is the risk of experimentation? Does the customer need to pay for a proof of concept? Does the customer need to requisition IT resource (new servers, open up a firewall port, etc) to enable your product to showcase its benefit? As with the MySQL comment above, can the customer experiment and test the value proposition without material risk or expense?

What is the time to integration? Can the product provide standalone value that obviates the need for day one systems integration, a la SFA? To the extent integration is required, how standardized are the interfaces to relevant up and downstream systems that add value to the solution?

The consumer internet offers useful lessons and direction for the enterprise space. Customers self-provision, self-validate, self-integrate, and self-configure.

The dinner offered some great ideas and insights, and I look forward to seeing the great new companies that are currently being hatched on campus.

Wednesday, January 18, 2006

Share of Revenue and Profits


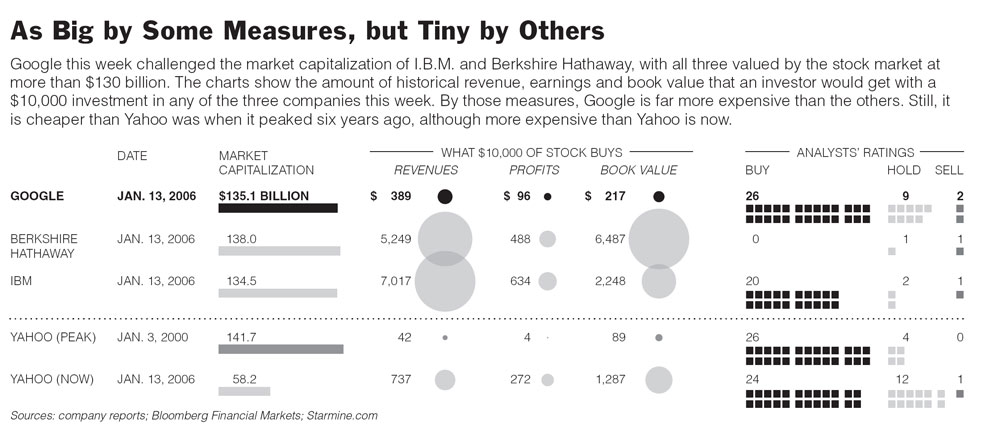
The NYT recently published an interesting article on the occasion of Google's market cap matching that of Warren Buffet's Berkshire Hathaway.

See the attached chart. The analysis looks at the relative claims of $10,000 worth of IBM, Google, Yhoo today, Yhoo peak valuation, and Berkshire Hathaway shares on respective revenues and net profits .

The analysis illustrates that a company's improvement in fundamentals may not be matched by a corresponding improvement in stock price. YHOO is down 66% from its peak while $10,000 of YHOO stock now has claim to 17.5x more revenue, 68x more net profit, and 14.5x more book value than at its peak valuation.

The separation from fundamentals and valuation, realistic forecasts and market cap, etc become particularly problematic when market sentiment changes. The questions of where is the floor and what is the intrinsic value are begged by the separation. With GOOG swinging $15 in a given day, it may pay to think about the analysis and YHOO's recent history.

Thursday, January 12, 2006

RSS Ad Stats


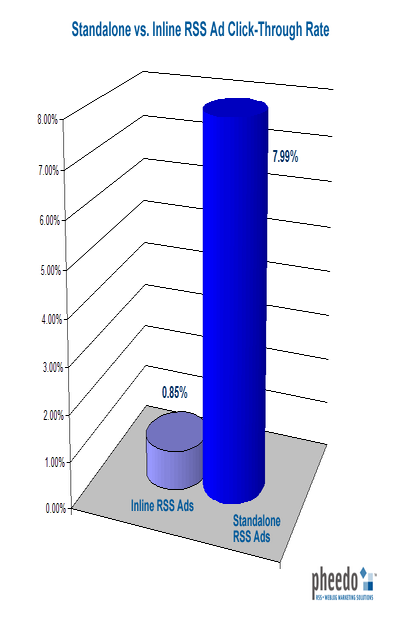
With RSS traffic and RSS reader adoption booming, ad impressions on traditional sites will inevitably go down. Web publishers will need to work out how to make money off of the RSS r/evolution via embedding ads in RSS.

For some very useful statistics on RSS advertising click-through-rates and RSS reader behavior, check out Pheedo's blog - Pheed Read #1 and # 2.

The feeds are instructive and suggest that RSS ads significantly outperform traditional web advertising wrt CTRs. Furthermore, given RSS subscriptions allow for more effective targeting and segmentation it is likely that the CPCs will be higher than with traditional on-line ads. Web publishers may find that driving RSS usage increases ad-related revenues despite a decline in "home site" web-site page views.

I would love to talk with people working actively in this area. Thanks to Pheedo for the data.

Wednesday, January 11, 2006

Living History - Sun Founders Panel

Tonight, the Computer History Museum in Mountain View hosted a fabulous event with the four founders of Sun - Vinod Kholsa, Scott McNealy, Andy Bechtolsheim, and Bill Joy. If you enjoy history and technology, I encourage you to come to future events and to support the only museum in the world dedicated to the collection and preservation of the software, documentation, hardware, images, and personal histories that represent the innovation and advances in IT.

The wonderful reality about the technology industry is that a significant number of IT industry pioneers and innovators are not only still with us (Jobs, Joy, Bechtolsheim, etc), but also remain vibrant participants in the economy they helped to create. Tonight really was living history with the people on stage recounting the founding of Sun in 1982 and the adoption of open systems, Unix, RISC, Java, network based computing, the constant ying and yang of fat vs thin clients, and the MSFT vs Sun world views.

Sun's sales in the first six years - $8.5m to $1bn- testify to its force as disrupter, and yet I have to tip my hat to the company and founder's staying power. Here we are 24 years later and 50% of the founders remain employees and Sun remains a force in the market place.

WRT disruption, it is instructive to note that open systems were lightly regarded by the investment community in 1982, which is very similar to Marc Benioff's experience raising money for SaaS-based CRM in the late 1990s. The common elements in both examples appear to be a price/performance ratio improvement and an alignment to the customers' interests that the competition's business model did not allow for. Yet the investment community, in both instances, reflected the incumbent's world view. It seems to be a truism that large companies in technology can innovate (Xerox Parc being the poster child) but that they remain vulnerable with respect to brittle cost structures, business models, and organizational dynamics that make it difficult to use the very technologies their research labs are innovating. Perhaps the best answer to "why can't a large company do what you do Mr Start-up," is to say they probably can but they can't afford to - history, that is living history, says that's true.

Wednesday, January 04, 2006

Personal Equity

Steve Bird of Focus Ventures wrote an interesting paper on what drives venture capital returns.

The paper looks at two investment cycles: the PC era of 1983-1987 and the Internet boom of 1997-2001. In the former era, the top 50 firms represented 13% of the industry and captured 44% of the value created. In the latter era, the top 50 firms represented 4% of the industry and captured 66% of the value created.

The moral of the tale to LPs is that if you cannot get your money in a top firm then don't invest in the asset class.

Click above to get the PDF.

Friday, December 30, 2005

Silicon Beat

Thanks to Matt over at Silicon Beat for recently profiling my blog. Silicon Beat is part of my daily routine and the site and reporting are consistenly good sources for the latest in the technology and start-up world.

Matt's reference to Hummer Winblad suggests that the firm has been quiet of late. It is worth noting that Hummer Winblad has been an active and successful software investor through three major technology cycles: PC, client/server, and the Internet era. The firm's track record of successful investments includes Arbor Software, Net Dynamics (sold to Sun), Adforce (sold to CMGI), Powersoft (merged with Sybase), Scopus (sold to SEBL), and Wind River.

In the past 18 months, the firm led investments in 14 companies including Akimbi, Palamida, Scalent Systems, Cittio, and ActiveGrid. Active portfolio companies include Omniture, Voltage Security, and Employease.

Thanks again to Matt for the post and to the entrepreneurs who read Silicon Beat, please be in touch:)

2005 Redux

According to Feedburner's Item Stats, the following posts topped this blog's most read list. Happy New Year and here's to a wonderful 2006.

Running on Empty
Search: The Rise of Specialization
The Golden Age of IT Buying and What Does it Mean for Investors
H1-B Aliens and the Myth of Free Labor Markets
Sales Forecasting
Sales Management
IBM: Standards, Customer Alignment, and Ecosystem-based Competition
The Cost of Optimism
Pat Your Head and Rub Your Tummy

Friday, December 23, 2005

Absurd Athleticism

Watch this Russian video for some incredible footage. It is sad to see such talent amidst such poverty. Hopefully, the market is efficient and Hollywood talent scouts are on their way.

Wednesday, December 21, 2005

Cap Table Hygiene

Venture capitalists are very much tabla rasa investors. One frequently hears about deals with "no hair," "plain vanilla terms," and good hygiene. Conversely, deals that come with cap table challenges (too many investors, too much prior preference, or onerous terms granted to a prior round) are often dead on arrival.

Why? My view is that company formation and growth is hard enough - one has to deal with market risk, technology risk, team risk, downstream financing risk, etc; therefore deals that layer "bad organizational/legal hygiene" as an additional risk factor into the investment evaluation tend to fail to secure investment.

In thinking of starting a company, it is worth understanding the VC industry's attraction to greenfield situations and is well worth thinking through two specific capitalization challenges that often create downstream pitfalls.

  1. Too Many Founders

A typical Series A sees the following equity ownership distribution: VC syndicate 50%, option pool 20%, founders 30%. Each subsequent financing will see founders diluted by roughly 20% per financing, such that after three rounds the founder shares represent 30%*.8^2, or 19.2% of the company. The per founder math is very simple - founder shares/# of founders. It almost seems redundant to state that too many founders can greatly impact the downstream economics of the founders, however, I have seen very smart, experienced founding teams launch with 5-6 founders and come to realize later that the per founder ownership in the entity creates real incentive problems. The VCs will rarely take less than 40-50% of a Series A and the pool is almost always 20%. Therefore it is important to think through the distribution of the remaining shares to ensure that each member of the team is truly required to get the company off the ground. Teams of 2-3 founders seem to be the norm and cap table issues, questions about equity (wrt fairness), often arise if the team gets much bigger.

2. Too Many Common Holders

All things being equal, the number of common shareholders is inversely proportional to a VC firm's interest in funding a company. The brutal reality of company formation is that often one must take capital from as many angels as necessary. While a small number of qualified angels can add needed runway and perspective, too many angels creates shareholder issues that may impact downstream financings, acquisitions, and legal liability. In raising angel money, try to limit the number of investors required to hit the financing target. When shareholder consents are required - financings, acquisitions, etc - the logistics of rapidly getting approvals can be problematic. I have seen some buyers require full shareholder consents, even if not legally necessary, in order to limit downstream problems relating to minority shareholder lawsuits.

Reality often dictates the necessity of sub-optimal strategies, however, if you can think through how many founders and how many angels to have in your next company you can limit the negative impact of "bad hygiene" on a venture financing.

Friday, December 09, 2005

Hip Hop Web

While listening to Tupac in the car today, it struck me that web 2.0 and rap music have a great deal in common.

The democratizing effect of "two tables and a microphone" allowed people without instrumental training to create wonderful music. Similarly, today's web tools are enabling thousands of web users to create content and applications without deep knowledge of programming languages and technology. Mashups are the web equivalent to rap's sampling, code jams the analog to rap's freestyle battles, beta launches the equivalent to demo tapes, shout-outs the analog to track-backs, Apple's Garageband software similar to Typepad or Jotspot. Moreover, the blogosphere and rap are perhaps the most self-referential creative mediums known to man, whereby songs and posts build off one another in a call and response manner. Mashup's are experiments that create rich blends of underlying applications, as rap tunes are created via the synthesis of jazz, funk, and soul classics. Creativity and innovation is redefined from ground-up development (100% original material) to innovations on the margin. Finally, web 2.0 and rap are both driven by young innovators, often around project-based interaction rather than long-term relationships.

The steady advance in web tools is introducing on-line creativity, rather than simply on-line consumption, to millions of people. As with rap, I think the world is richer for it.

Monday, December 05, 2005

How to respond to Nigerian Spam Mail

The ingenuity and implicit humor found in Nigerian spam mail inspired a close friend of mine, Mike Flynn, to send this incredicle response.

This could be the funniest thing I have read in a long time . Well done Mike.


Re: Next of Kin

Dear Paul,

By a most uncanny coincidence, I am also soliciting a barrister, preferably a national of your country, who worked with Shell development. By a most unfortunate series of events, I was being held hostage in the trunk of the car that claimed the lives of your client. Fortunately I was blown clear of the wreckage and was able to make my way through the jungles of Nigeria to the Plains of Arjuna dragging a dozen large boxes that I was informed by the sister of the mailman who claimed to be the ilegitimate heir to the throne of Uganda, Mr. Yanindada N'Golo Botticelli Vespa, manservant to your client, contained bars of gold bullion!

When I made it to the Baltic sea I was able to obtain safe passage (after many months of hardship as a fish monger's wife) in a freighter to northern Llapland where I met a Nordic Shaman named Odin who told me you would be contacting me after 23 full moons to fulfill my economic desires.

Paul, I feel I can trust and confide in you and feel from your words that you are a man of God and the people who will help me in my time of need. If you can help me with my immediate need of exporting 300,000,000 pink plastic monkeys to Jakarta I will then be in a better position to provide assistance in routing US$106M to my accounts in Lichtenstein.

be the ball Danny,
truly,
M

Dear Sir/madam

I am Barrister paul debayo Solicitor. I am the Personal Attorney to Mr
Thomas Anindya, a national of your country, who used to work with
shell development company in Nigeria.On the 2nd of may 1999, my
client, his wife And their three children were involved in a car
accident along Sagbama Express Road. All occupants of the vehicle
unfortunately lost there lives. Since then I have made several
enquiries to your embassy to locate any of my clients extended
relatives, this has also proved unsuccessful.

After these several unsuccessful attempts, I decided to trace his
relatives over the Internet, to locate any member of his family but of
no avail, hence I contacted you. I have contacted you to assist in
repartrating the money that belong to my client before they get
confisicated or declared unserviceable by the bank where this huge
deposits were lodged.

Particularly, the Bank where the deceased had an account valued at
about $30million dollars has issued me a notice to provide the next of
kin or have the account confisicated within the next ten official
working days. since i have been unsuccesfull in locating the the
relatives for over 3 years now I seek your consent to present you as
the next of kin of the deceased since you are from the same country
and bear the same last name ,so that the proceeds of this account
valued at $30 million dollars can be paid to you and then you and me
can share the money. 55% to me and 40% to you,while 5% should be for
expenses or tax as your government may require, I have the certificate
of deposit that can be used to back up any claim we may make. All I
require is your honest cooperation to enable us see this dealt
through.

I guarantee that this will be executed under a legitimate arrangement
that will protect you from any breach of the law.Please get in touch
with me by my email to enable us discuss further.

I WILL OBTAIN AFFIDAVIT FROM COURT WHEN YOU RESPONS TO ME.

Best regards,

Esq:paul debayo
Thursday, December 01, 2005

New Web Site

Hummer Winblad launched our new web site yesterday.

The site provides a great overview of the firm, timeline of investments since founding in 1989, and our process.

For those of you who know the firm well know that John's dog is a key member of the team.

See if you can find an overview on our honorary senior canine leader.

Saturday, November 26, 2005

H1-B Aliens and the Myth of Free Labor Markets

A wonderful constant in this valley of innovation, is the amazing contribution of immigrants to our economy.

In my daily meetings with founding teams and start-ups, there is not a single company that does not have an emigre as a key member. The contribution of Indian, Chinese, Russian, and other nationals to our economy is beyond question and a vital source of our success. From professors, to engineers, senior managers, company founders, and venture capitalists, our current success and prosperity is very positively influenced by our ability to attract the best and brightest to work and study in our country.

Unfortunately, America, while often a champion of free trade, is not a practioner of free labor markets. While technology talent is perhaps the most important input in Silicon Valley's decades of innovation, the US government artificially caps and limits the number of ambitious immigrants to our economy. This year, the H1-B Alien visa program is limited to 65,000. Moreover, since 9/11 the US government has clamped down on graduate student visas; current visa application security checks take 67 days and the total process takes over 3 months . The pernicious effect red-tape is that gifted students are less likely to bother applying, thereby greatly weakening our future prosperity and welfare.

A recent GOA study found that:

  • "Lengthy waits to obtain a visa might lead Chinese students and scholars to pursue studies or research in countries where it is easier to obtain a visa. A consular chief in Chennai, India, agreed, saying that lengthy waits are also causing Indian students to decide to study in countries where it is easier to get a visa and, therefore, the United States could lose out on intellectual knowledge these visa applicants bring to our country"
  • "Many officials with whom we spoke cited specific examples where scientific research and collaboration was delayed or prevented due to delays in obtaining a visa. NASA officials at post also noted that up to 20% of their time is spent dealing with visa issues when they should be focusing on program issues."
  • "According to several surveys, scientific research was postponed, jobs were left unstaffed, and conferences and meetings were missed as a result of the delays."

True globalization requires the seamless flow of ideas, products, and talent. While the world is moving in the right direction, the future of the Valley requires that we make it easy for the world's best to study, work, and contribute to our economy.